
Show Me
Lecturer
Faculty of Law and Business, Peter Faber Business School
Areas of expertise: financial reporting; International Financial Reporting Standards (IFRS); IFRS for SMEs; SME financial reporting and simplified disclosures; sustainability and ESG reporting; IFRS S1/S2 and AASB sustainability disclosure standards; accounting regulation and reporting quality; accounting judgement and decision-making; decision-usefulness of financial information; behavioural accounting
Phone: +61 2 9465 9652
Email: [email protected]
Location: ACU North Sydney Campus
HDR Supervisor accreditation status: HDR Supervisor (Full)
ORCID ID: 0000-0001-9180-4001
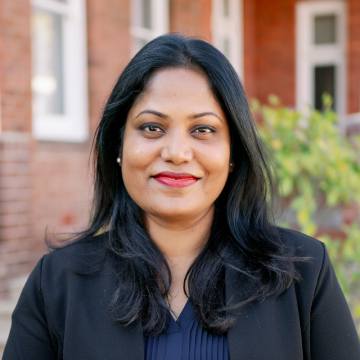
Dr Dinuja Perera is a Lecturer in Accounting at the Peter Faber Business School, Australian Catholic University (ACU). She holds a PhD in Accounting from Macquarie University and is a Chartered Accountant (CA ANZ). She has extensive academic and research experience in accounting, having previously held academic positions at Macquarie University and the University of Kelaniya, Sri Lanka.
Her research focuses on financial reporting, international accounting standards, sustainability reporting and the decision-usefulness of accounting information. A central theme of her research is how accounting standards and disclosure requirements influence financial reporting practices, professional judgement and the usefulness of information for different stakeholders.
Her research on small and medium-sized enterprises (SMEs) examines the adoption and implementation of International Financial Reporting Standards (IFRS), particularly IFRS for SMEs, and the implications of differential reporting frameworks for preparers and users of financial statements. Her current research extends this work by investigating Australia's simplified disclosure requirements (AASB 1060), with particular attention to whether reduced disclosure requirements meet the information needs of lenders and other users of SME financial reports.
Another key area of her research is sustainability and ESG reporting, particularly the evolving international sustainability disclosure framework under IFRS S1 and IFRS S2 and their Australian equivalents. Her current research examines voluntary sustainability disclosures, financial and double materiality, and organisational readiness for mandatory sustainability reporting. This work seeks to understand how existing reporting practices influence the transition to new sustainability disclosure requirements and the implications for corporate transparency and decision-making.
Her research also encompasses behavioural accounting, including professional judgement, confirmation bias and the influence of cognitive factors on accounting decisions.
Dr Perera has published research in internationally recognised peer-reviewed journals, including Accounting & Finance, Meditari Accountancy Research and Advances in Accounting. Her research has received support through competitive funding initiatives, including an Accounting and Finance Association of Australia and New Zealand (AFAANZ) research grant and an ACU Faculty of Law and Business research innovation grant.
As an ACU-accredited HDR supervisor, Dr Perera welcomes enquiries from prospective research students interested in financial reporting, international accounting standards, SME accounting, sustainability reporting, accounting regulation and behavioural accounting.
2026 – AFAANZ Research Grant Accounting and Finance Association of Australia and New Zealand (AFAANZ)
2026 – Faculty of Law and Business Research Innovation Grant: Australian Catholic University (ACU)